Capital / area
Lucknow |240, 928 sq km
Industrial investment and policy for Viksit Bharat 2047. Evidence reviewed as of 1 November 2026; document dates and unresolved gaps remain explicit.
Read or download investor brochure
Lucknow |240, 928 sq km
Nepal; Uttarakhand, Himachal Pradesh, Haryana, Rajasthan, Madhya Pradesh, Chhattisgarh, Jharkhand, Bihar; Delhi NCT. Use official map for small boundary segments.
Gangetic plains with Himalayan foothills to north and Vindhyan terrain to south; landlocked.
FY 26 current-price GSDP estimated₹ 30.80 trillion; IBEFApril 2026. FY 25 per-capita GSDP₹ 126, 304 (not household income).
₹ 24, 708 crore cumulative FDI Oct 2019-Mar 2026, IBEF quoting DPIIT; not annual manufacturing FDI.
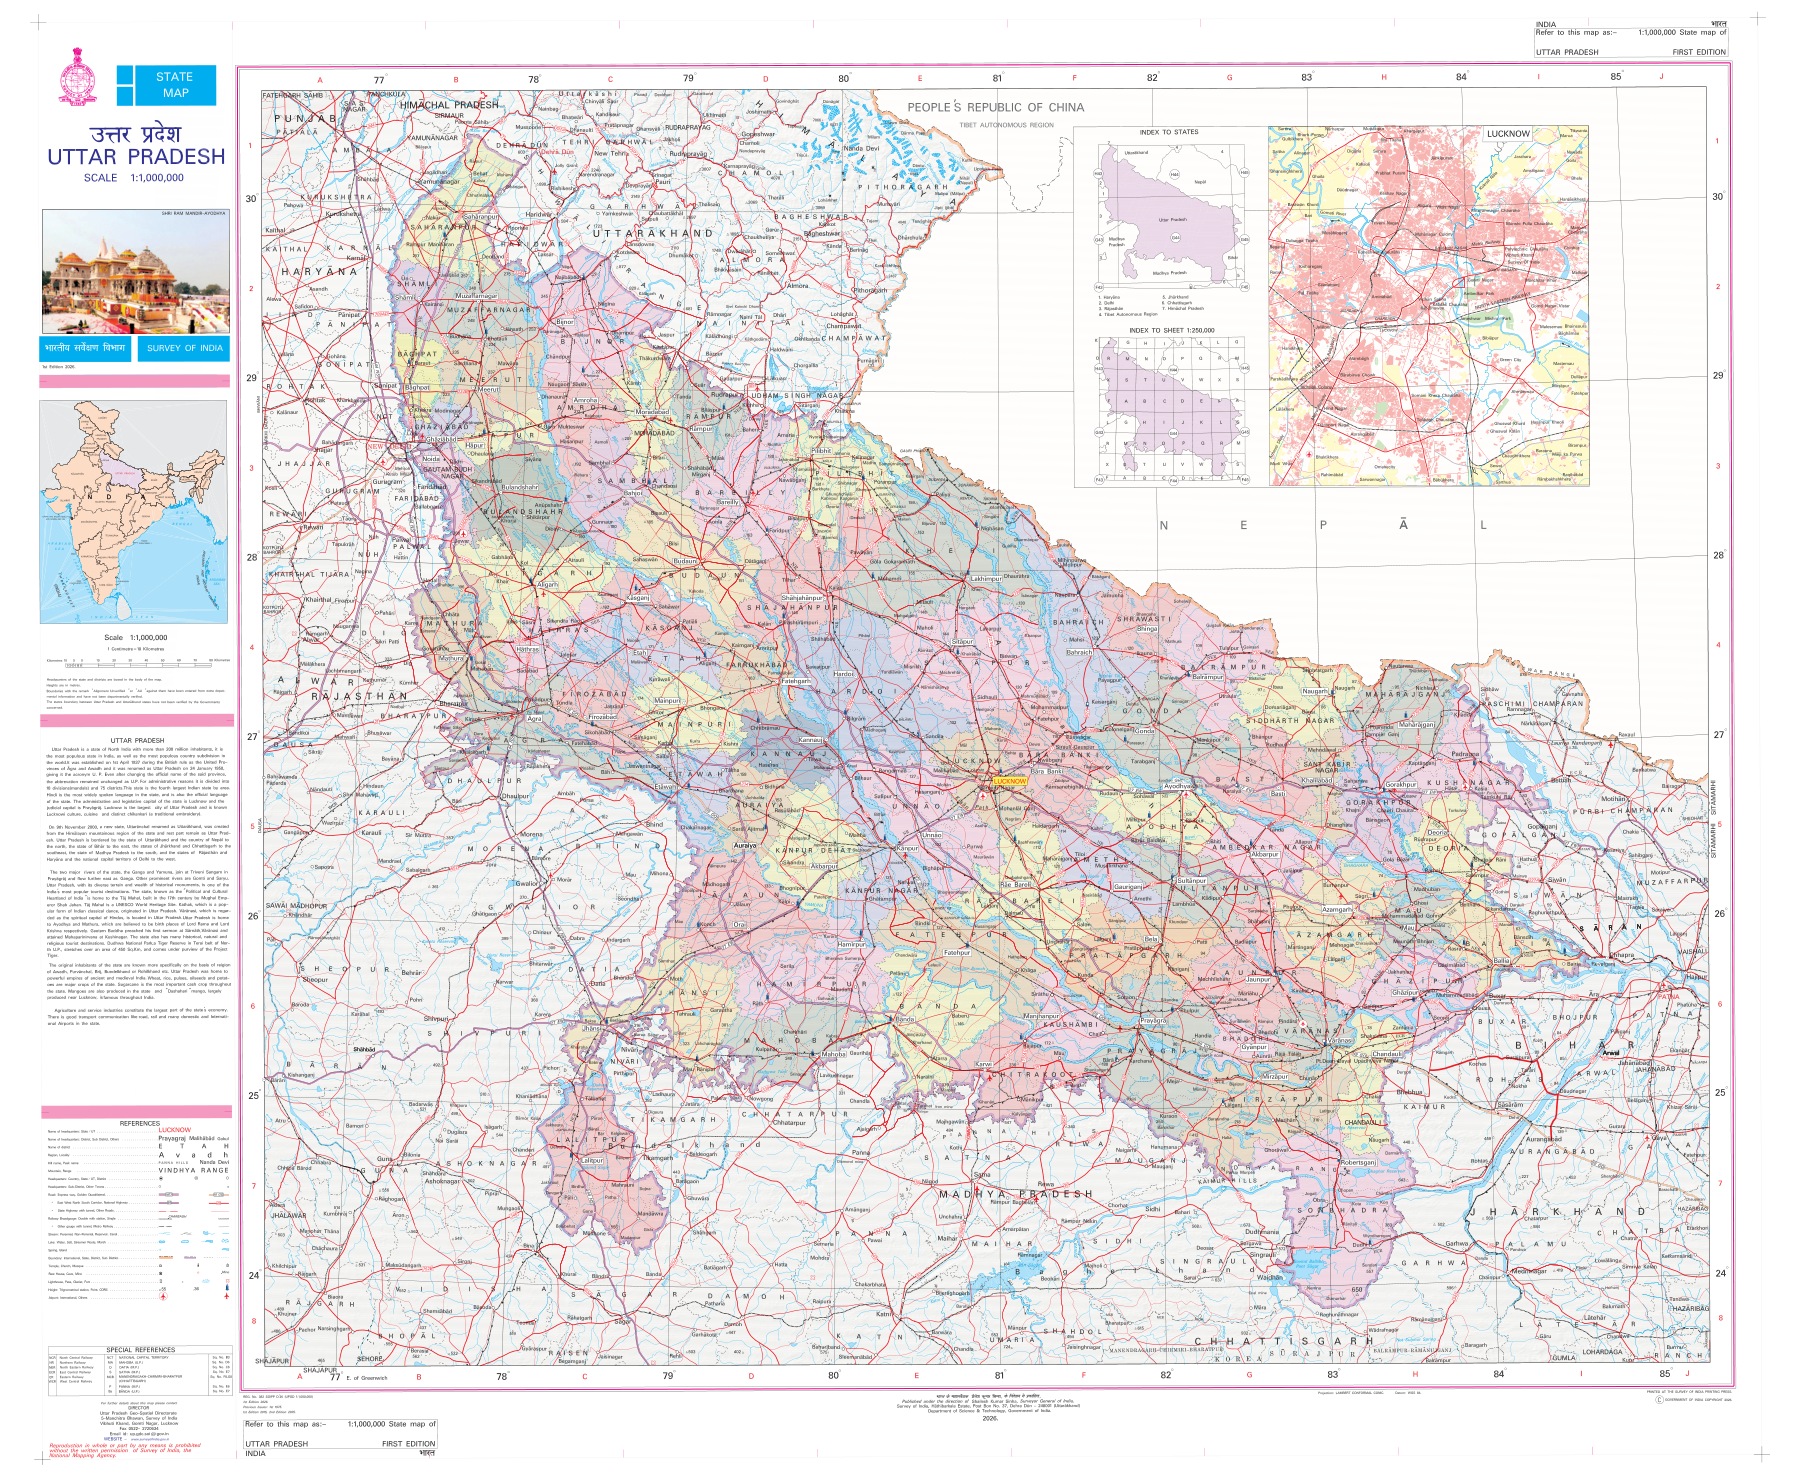
Official geographic context, resized; original source retained. UPMAP
Evidence. Official Invest UP identifies established electronics concentration and new 2025 component policy.
Commercial case. Supplier proximity and NCR market access can support components/industrialelectronics tied to anchor orders.
Exposure. Customer concentration, imported parts, obsolescence, power-quality and eligibility for newer schemes.
Investment gate. Require anchor qualification, demand commitment, cleanroom/power assessment and current 2025 amended policy comparison.
Evidence. Food Processing 2023 route and agriculture base; 35%capital support headline has defined asset categories.
Commercial case. Source-region processing plus NCR/urban distribution merits comparison at individual commodity level.
Exposure. Seasonal utilisation, water availability, food standards and cold-chain economics.
Investment gate. Proceed with procurement contracts and capacity utilisation sensitivities; subsidy should follow profitable base economics.
Evidence. Six corridor nodes plus existing manufacturing base; 2026 government press release distinguishes investment commitments.
Commercial case. Pursue established buyer qualification gaps and components, not generic speculative defence capacity.
Exposure. Long procurement cycles, export/security licensing, testing accreditation and customer concentration.
Investment gate. Obtain buyer RFQ/qualification plan and node service readiness before land commitment.
Evidence. IT 2022 first amendment published 7 Sep 2026; GCC 2024 implementation rules published 2026.
Commercial case. Compare NCR experienced talent against Lucknow/other-city cost and hiring pipeline for appropriate functions.
Exposure. Attrition, wage inflation, data/client requirements; legacy policy figures may be stale.
Investment gate. Model total occupied-seat cost, retention and redundancy; apply latest amendment and correct GCCdefinition.
Status. Established ecosystem; specific vacant ready plots unverified.
Detail. Electronics/ITscreening. NICDC classifies Integrated Industrial Township Greater Noida as developed.
Status. NICDC separates transport/logistics hubs as nearing completion; do not call all operational.
Detail. Checkterminal commissioning, trainservices and last-milequotes.
Status. Six nodes at different stages; land identified or committed investment is not finished capacity.
Detail. Aligarh, Agra, Jhansi, Chitrakoot, Kanpur, Lucknow; inspect plot-specific power/water/access.
Status. NICDC new projects; no assumedreadyland.
Detail. Compare futureopportunity with establishedlocations and deliveryrisk.
Route. Agra-Lucknow / Purvanchal / Bundelkhand / Gorakhpur Link; Ganga links Meerut-Prayagraj.
Status. UPEIDA lists all five operational; Ganga inauguration recorded 29 April 2026.
Industrial relevance. Compare western electronics distribution, eastern food aggregation and Bundelkhand engineering on the actual plot-to-interchange route.
Investor test. Inspect legal heavy-vehicle access, bridge/loading limits, tolls, urban entry restrictions and seasonal delivery records; expressway frontage does not mean direct access.
Route. Dadri → Western DFC → JNPT; EDFC Ludhiana → Sonnagar serves the wider northern/eastern freight spine.
Status. WDFC fully operational per 8 September 2026 JICA release; EDFC commissioned.
Industrial relevance. For containerised components, machinery and manufactured exports, compare a Dadri-linked rail booking against all-road gateway alternatives.
Investor test. Obtain the container operator’s terminal pair, first-mile rate, train frequency, cut-off, empty-container supply and shipping-line connection. Separate DFC commissioning from Dadri/Boraki hub readiness.
Route. Ramnagar-Varanasi MMT → NW-1 → Haldia maritime interface.
Status. MMT developed; adjoining freight village and MMT railway integration remain separate development works.
Industrial relevance. A candidate for aggregated, less time-sensitive freight; assess load consolidation before committing a plant to the water route.
Investor test. Trial cargo-specific barge movement; validate draft, river season, handling loss, first/last mile and road/rail contingency.
Route. Lucknow / Varanasi cargo gateways; assess NCR plants against their actual airport routing.
Status. AAI describes cargo handling infrastructure; no current airline frequency, payload or commodity acceptance verified.
Industrial relevance. Use air for urgent components, samples or suitable high-value/perishable cargo only after a service quotation. Passenger access supports management travel, not proof of freight availability.
Investor test. Confirm customs scope, cut-off, cold-chain hours, airline payload and transfer airport. Noida airport cargo capability is not assumed in this assessment.
Benefits. Stamp duty: 100%Bundelkhand/Poorvanchal; 75%Madhyanchal/Paschimanchal except GBN/Ghaziabad; 50%GBN/Ghaziabad.
Conditions. Large>₹ 50 cr<₹ 200 cr; Mega₹ 200-<500 cr; Super Mega₹ 500-<3000 cr; Ultra Mega≥₹ 3000 cr. MSMEs need their own route.
Status. Current Invest UP listing; read implementation SOPs and subsequent orders.
Benefits. Choose ONE: capital subsidy / net SGST reimbursement / PLI top-up. Base capital rates 10-30%ECI by district/category, paid 10-20 years.
Conditions. Annual caps and capacity-use conditions matter; full GCM requires 75%peak capacity after first year (first year 40%threshold). Do not add all three.
Status. Original PDF and official current summary verified.
Benefits. Newunit 35% eligible plant, machinery and technicalcivil expenditure, cap₹ 5 crore; 100%stamp duty exemption.
Conditions. Separate conditions, eligible cost, sanction and 2025 implementation guidelines; expansionpercent differs across official summaries, so exclude expansionrate until reconciled.
Status. Original PDF downloaded; benefits cross-checked official summary.
Benefits. Updated policy covers capital/operating expense, payroll, skills, exports and relocation routes.
Conditions. Use 7 Sep 2026 amended original; do not reuse unamended 2022 rates. District classification and eligibility define actual support.
Status. Current amendment downloaded 24 pages.
Benefits. Dedicated GCCroute; rules state effective date 7 May 2025.
Conditions. Obtain original policy plusrules and qualifyingunit thresholds; do not conflate branding year 2024 with notification 2025.
Status. Rules located; amounts not independently audited.
Benefits. Electronics Component Manufacturing 2025(first amendment); compare legacy Electronics 2020; Defence/Aerospace; MSME 2022; Logistics 2022; EV 2022; FDI/FCI 2023.
Conditions. Applicableproject must select correctroute; olderpolicy still beinglisted is not proof openapplication window. Check incentives stacking, sunset and expenditure eligibility.
Status. Current official directory identifies routes; project-specific originals required before financial reliance.
Multiple established industrial and urban markets allow sector-specific location choice.
Regional incentive differentiation creates alternatives to NCR for suitable projects.
A large state average conceals different logistics, wages and suppliers across districts.
Landlocked exports need a verified inland freight chain; corridor proximity alone does not prove affordable service.
Components, food value addition and qualified defence supply can build around demonstrated ecosystems.
Choose location by delivered cost and buyers; compare mutually exclusive subsidy routes by discounted cash flow.
Investment proposals and identified corridor land can be mistaken for operating capacity.
Rapid policy amendments can invalidate old headline benefit tables; September 2026 ITrevision is an example.
Constraint. Inland location requires a port leg, but a dedicated western freight corridor now exists.
Intervention. Aggregate anchor-customer export volumes and procure through-terminal/port service instead of separate uncoordinated legs.
Action owner. Manufacturer consortium with container train operator and freight forwarder
Opportunity. Shared export consolidation, vendor-managed inventory and packaging near a verified rail terminal.
Commercial gate. Minimum contracted loads and delivered-cost saving after handling, inventory and empty repositioning.
Residual risk. Missed vessel connection or underfilled trains can erase nominal line-haul savings.
Constraint. District-level first/last-mile conditions differ; LEADS records congestion and winter-fog concerns.
Intervention. Locate truck holding/cross-dock outside the constrained urban leg, schedule dispatch windows and maintain alternate routes.
Action owner. Estate developer, logistics operator and road/local authority
Opportunity. An independently viable consolidation or cold-chain node serving several plants.
Commercial gate. Paid anchor contracts, permitted land use, measured seasonal dwell time and resilient utilities.
Residual risk. Public-road improvements and adverse-weather controls are outside the plant’s sole control.
Constraint. A developed river terminal does not guarantee a complete rail-water service chain.
Intervention. Run a volume-backed pilot using existing access and contract a road fallback before sizing terminal-linked assets.
Action owner. Cargo owner, barge operator and IWAI/terminal operator
Opportunity. Cargo aggregation and handling services around Varanasi for suitable non-urgent products.
Commercial gate. Quoted service, demonstrated handling compatibility and all-in cash-cycle advantage.
Residual risk. Draft variability, low utilisation and delayed rail integration remain possible.
Assessment. Project-specific evidence required; no numerical score invented
Evidence required. Customerlocations, actualfreightquotations, delivery SLAs
Assessment. Project-specific evidence required; no numerical score invented
Evidence required. Title/allotment, permitteduse, powerquality, waterallocation, effluentcapacity
Assessment. Project-specific evidence required; no numerical score invented
Evidence required. Role-specificavailableworkers, wages, trainingcost, retention
Assessment. Project-specific evidence required; no numerical score invented
Evidence required. Operativepolicy, application window, sanction, eligible cost, claimtiming, stacking
Assessment. Project-specific evidence required; no numerical score invented
Evidence required. Siteflood/drainage, consents, waterstress, constructionmilestones
Current wage, skill vacancy, industrialwater/power reliability andland-price quotations not independently measured.
No guaranteedprojectreturn or ease-of-doing-business score.
Central FDI, tax, customs, labour, environment, remittance andschemeconditions must be incorporated from centraldossier.
Use SOImap for allneighbours; state prose neighbour lists inconsistent.
Do not call proposeddata-centrecapacity operational or assume everydefencecorridorplot ready.
No current transport quote, plot approach audit, train/airline schedule, customs commodity acceptance or shipment trial obtained.
Airport and inland-terminal installed infrastructure do not establish a product-specific service.
Central policy, FDI, tax, customs, environment, workforce and remittance guide · Single canonical evidence repository
STARTUP POLICY · CHECKED 4 NOVEMBER 2026
2026 policy and official operational-guidelines PDF retrieved; older 2020/2022 material is not the current new-applicant policy.