Capital / administrative centre
Jaipur
Industrial investment and policy for Viksit Bharat 2047. Evidence reviewed as of 1 November 2026; document dates and unresolved gaps remain explicit.
Read or download investor brochure
Jaipur
342, 239 km² (Rajasthan Resident Commissioner geographical profile)
Large landlocked state spanning arid west and Aravalli/eastern regions. Water balance and market corridor matter more than land area alone.
Punjab, Haryana, Uttar Pradesh, Madhya Pradesh and Gujarat; international border with Pakistan.
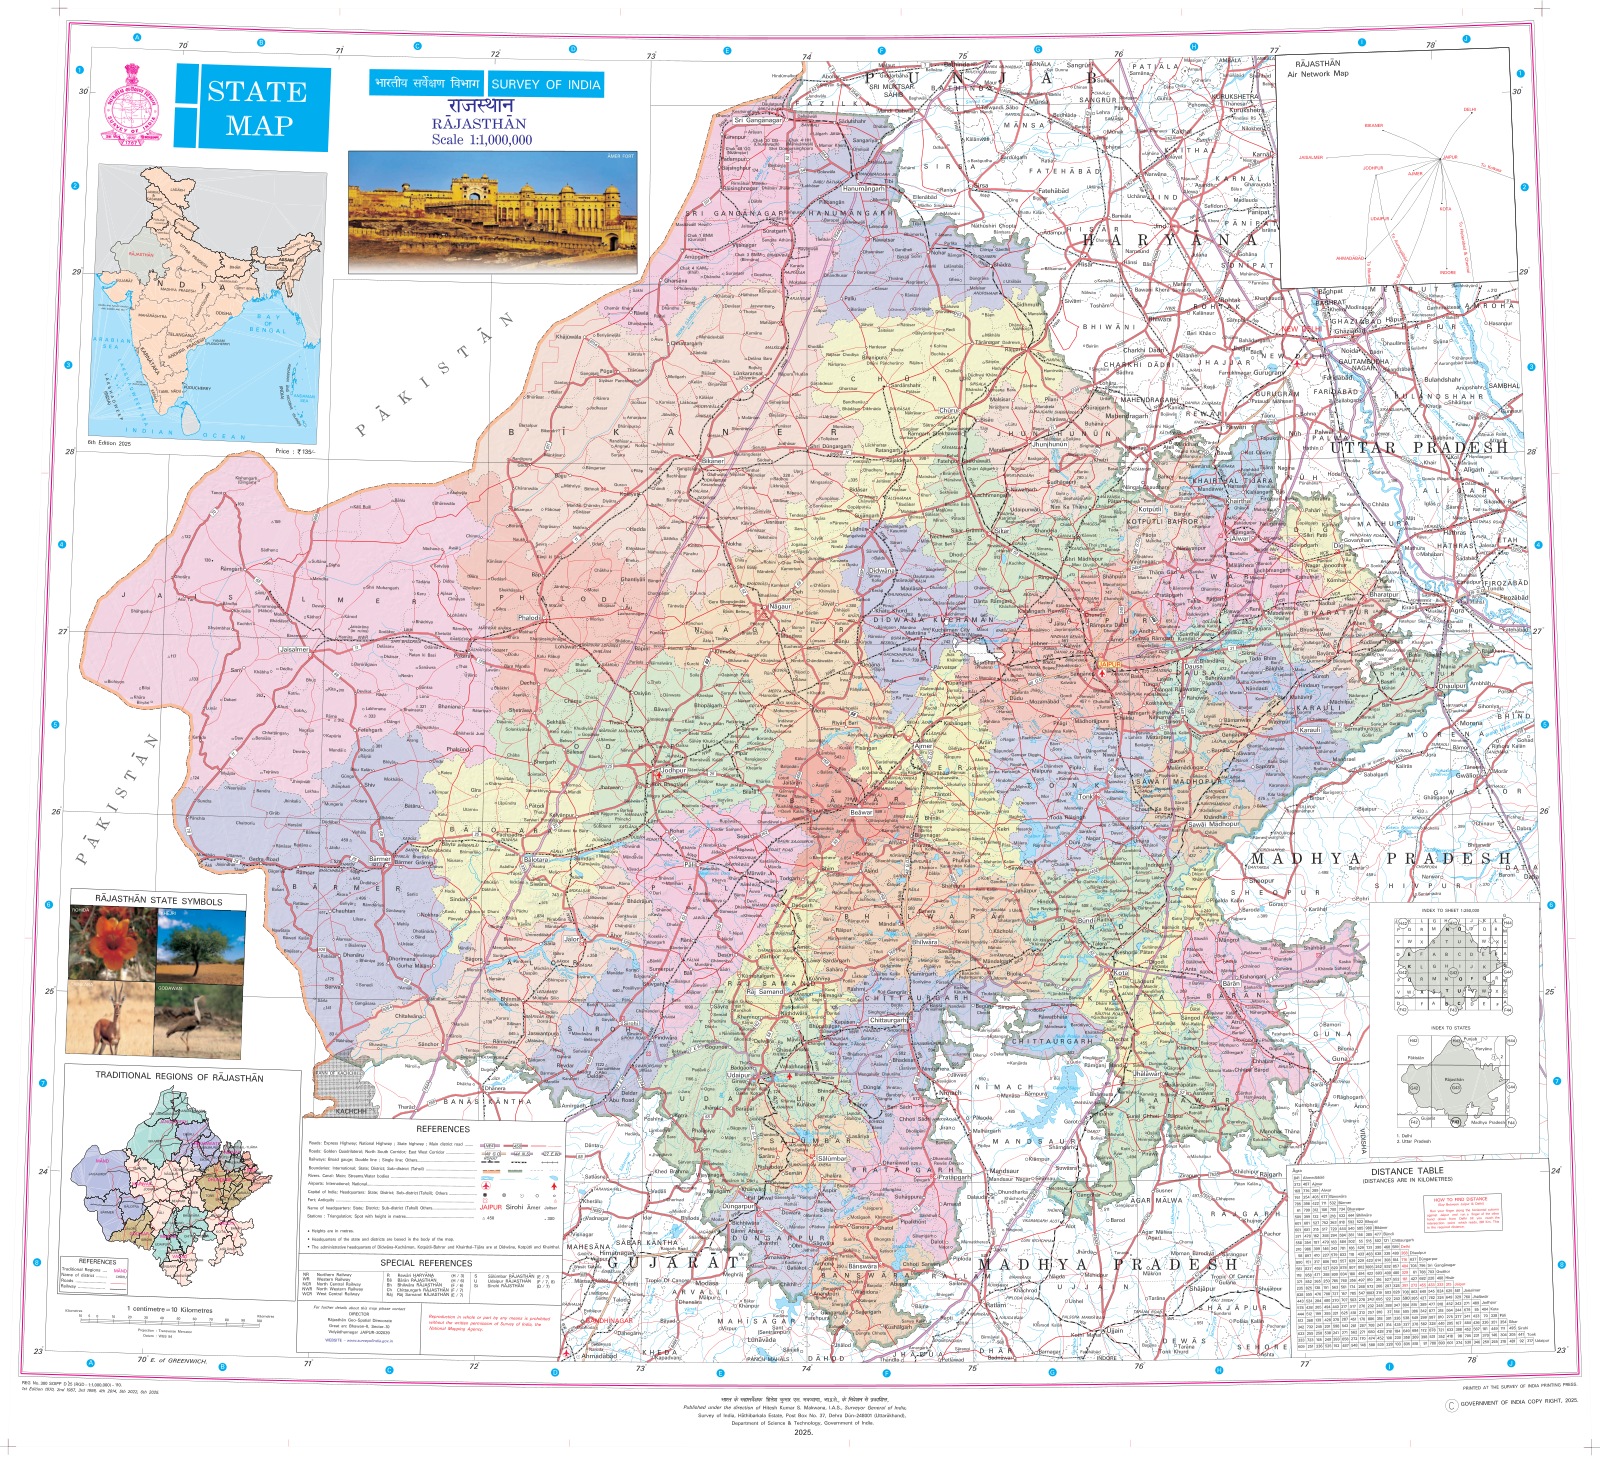
Official geographic context, resized; original source retained. RJMAP
Evidence. Industrial Development Policy 2026 identifies established manufacturing clusters and corridor-led development.
Commercial case. Target approved suppliers near NCR buyers while comparing locations outside congested production nodes.
Exposure. Water, NCR emissions restrictions and buyer concentration.
Investment gate. Verify HSIIDC/RIICO plot jurisdiction, water allocation, CAQM applicability and buyer nomination.
Evidence. The policy identifies textile clusters and environmental-infrastructure needs.
Commercial case. Prioritise higher-specification products and recycling/treatment services rather than assuming unrestricted wet processing.
Exposure. Water intensity, effluent disposal and textile-market volatility.
Investment gate. Confirm legally usable water, treatment capacity, buyer audits and product margins.
Evidence. Industrial policy recognises mineral-based industry and cluster development.
Commercial case. Locate cutting, finishing and engineered products around feedstock and logistics, with contracted buyers.
Exposure. Silica exposure, quarry legality, waste and freight cost.
Investment gate. Trace authorised raw-material source, dust control and delivered export economics.
Rationale. Target approved suppliers near NCR buyers while comparing locations outside congested production nodes.
Rationale. Prioritise higher-specification products and recycling/treatment services rather than assuming unrestricted wet processing.
Rationale. Locate cutting, finishing and engineered products around feedstock and logistics, with contracted buyers.
Assessment. NH 48 and Delhi-Mumbai corridor geography are key to eastern industrial screening; desert distance and last-mile road quality must be included.
Status. Mapped roads; no parcel travel-time promise
Assessment. CONCOR lists Kathuwas, Kanakpura, Bhagat Ki Kothi, Mandalgarh, Khemli and Kota. Western ports are alternatives for export quotation, not guaranteed links from every terminal.
Status. Existing listed terminals; route/slot confirmation required
Assessment. Jaipur is a business-access and cargo-screening gateway; cargo product acceptance, customs and capacity require current operator evidence.
Status. Facility reference only
Assessment. No inland-water freight base case. Water-stressed locations require a defensible source, allocation and reuse plan before process selection.
Status. Hydrological constraint; no river-distance shortcut
Benefits. Manufacturing Asset Creation Incentive offers alternative SGST, capital or turnover-linked pathways; exemptions and boosters remain eligibility-dependent.
Conditions. Choose a permitted alternative; EFCI, enterprise size, area and commercial-production/entitlement-certificate conditions apply.
Status. Operative scheme says until 31 March 2029 or replacement earlier; no project entitlement assumed.
Checked pages. Scheme operative-period/eligibility and manufacturing ACI provisions; exact numerical table not reproduced
Benefits. Provides industrial-development framework, cluster and infrastructure priorities.
Conditions. Enabling objectives are not an automatic cash entitlement; read fiscal support through RIPS and applicable notifications.
Status. Original 2026 policy retrieved.
Checked pages. Cluster, infrastructure and sustainability chapters
Benefits. Supports development of logistics infrastructure and multimodal services.
Conditions. Facility category, investment and RIPS route must be checked; proposed infrastructure must not be labelled operational.
Status. Original retrieved; no unverified rate included.
Checked pages. Scope and logistics-infrastructure provisions
Established textile, mineral and manufacturing clusters reduce ecosystem discovery cost.
Several inland container locations support gateway comparisons.
Water availability can constrain otherwise attractive sites.
Large distances create materially different corridor economics.
Recycling and effluent services can support compliant clusters.
Value-added mineral and technical-textile products can improve freight value density.
Drought and competing water demand remain physical risks.
NCR production may face changing air-quality restrictions.
Constraint. Water-intensive production
Intervention. Audit and implement reuse/ZLD with cluster participation
Owner. Investor, RIICO and pollution-control authorities
Opportunity. Water-efficiency and treatment services
Prerequisite. Legally allocated input water and approved disposal
Residual risk. ZLD cost and concentrate disposal remain
Constraint. Long inland haul
Intervention. Compare ICD-led consolidation with direct trucking
Owner. Exporter and rail/logistics providers
Opportunity. Shared container services
Prerequisite. Committed volume and verified gateway acceptance
Residual risk. Empty repositioning and vessel disruption remain
Constraint. Commodity stone margins
Intervention. Invest in dust-controlled finishing and traceability
Owner. Processor and buyers
Opportunity. Higher-value architectural products
Prerequisite. Legal raw-material chain and contracted specifications
Residual risk. Construction-cycle exposure remains
RIPS numerical choices and combined ceilings require a clause-level project model; no blanket subsidy percentage is used in the brochure.
No guaranteed subsidy cash flow: validate eligibility, budget, application acceptance and stacking for the particular legal entity before financial close.
Cargo, port, railway service frequency, terminal capacity, routes, freight quotes, water allocation and plot availability require project-specific current evidence. No passenger flight is represented as a scheduled freighter.
Central FDI/FEMA, customs, tax, sector licensing and scheme windows are to be read with the common national legal guide; state incentives do not override them.
Central policy, FDI, tax, customs, environment, workforce and remittance guide · Single canonical evidence repository
STARTUP POLICY · CHECKED 4 NOVEMBER 2026
Official policy reviewed with iStart-stage and evaluation conditions.